Ambuja Cements Limited, part of the Adani Portfolio, reported its performance for the quarter ended September 30, 2026, highlighting capacity expansion, product premiumisation and cost management amid seasonal and external challenges. Vinod Bahety, Whole-time Director and CEO of Ambuja Cements, said the company continued to focus on quality growth despite monsoon-related disruptions, higher energy costs and geopolitical uncertainty. Improved trade and premium product sales, along with operational efficiencies, supported the company’s performance during the quarter.
Ambuja commissioned 4.6 million tonnes per annum (MTPA) of cement capacity in Q2 FY27, with another 5.6 MTPA expected to ramp up during the second half of the financial year. The company remains focused on reducing its cost to ₹4,250 per tonne by FY27. Total cost stood at ₹4,410 per tonne in Q2, while the cost excluding the impact of geopolitical conflicts was ₹4,182 per tonne.
Higher petcoke and coal prices, constrained coal availability, and increased diesel and packaging costs continued to affect the cement industry. Ambuja said disciplined pricing, a stronger product mix and logistics optimisation helped manage these pressures. The average primary lead distance declined from 265 km to 254 km, partly offsetting higher diesel costs.
The company expects volumes to grow ahead of the industry in H2 FY27, supported by stronger trade demand, calibrated institutional sales, new capacity and a higher share of renewable power. Recent cement price increases of ₹10–15 per bag are also expected to support pricing, subject to market conditions.
Ambuja shareholders have approved the proposed amalgamation of ACC Limited and Orient Cement Limited with Ambuja Cements at meetings held in September 2026. The proposal will now proceed to the National Company Law Tribunal (NCLT) for further approvals. The merger is expected to simplify the corporate structure, generate operating synergies and improve earnings per share. Completion is targeted for FY27, subject to regulatory and statutory clearances.
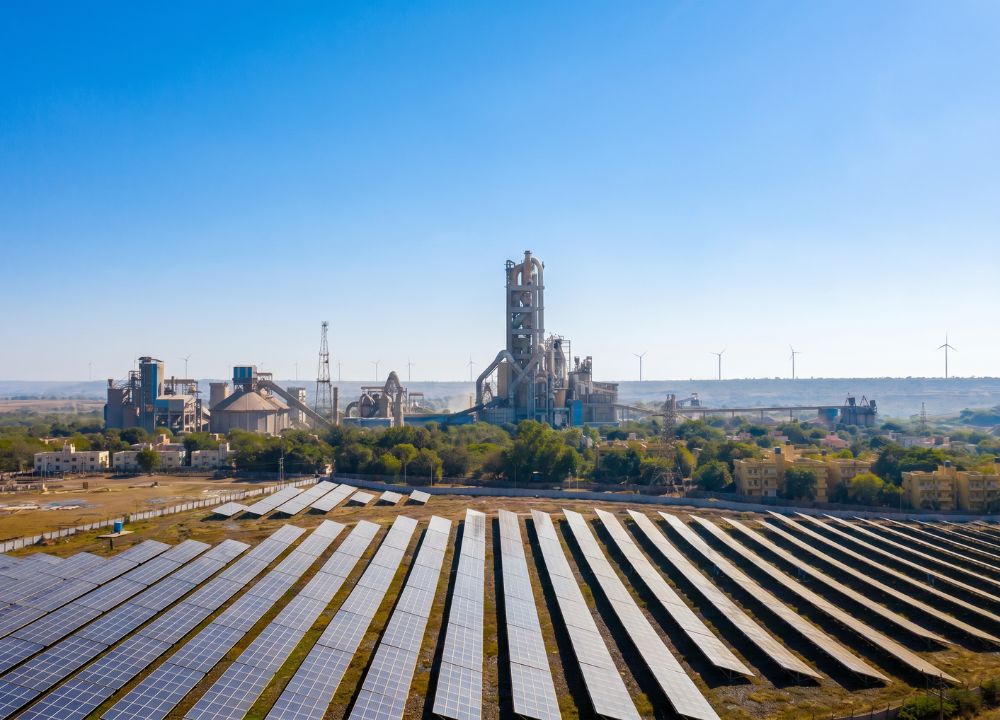
The company reported a net worth of ₹72,238 crore and cash and cash equivalents of ₹1,070 crore, maintaining a debt-free balance sheet. It continues to hold AAA/A1+ credit ratings from CRISIL, CARE, India Ratings and ICRA. On sustainability, Ambuja has partnered with Leilac Limited to assess a commercial-scale low-carbon cement pathway at its 6.6 MTPA Sanghipuram plant. The pre-feasibility study is targeted for completion by December 2026. The company also expects the first commercial application of Coolbrook’s RotoDynamic Heater technology to become operational by mid-2027.
Adani Cement planted 7.52 million trees by H1 FY27 against a target of 8.3 million. Ambuja and ACC also secured GreenPro certification for their blended cement portfolios. Ambuja Cements Limited is part of the Adani Portfolio and operates in the Indian cement industry. Its focus areas include manufacturing efficiency, logistics, renewable energy, digitalisation and the expansion of value-added cement products.